Save hours every week
Turn your bank statements (PDF) into Excel, CSV or OFX, without manual retyping.
Review checking accounts, credit cards, digital wallets and app-store billing for recurring payments. Use at least one full renewal cycle, often 12 to 13 months, to catch monthly, quarterly and annual charges. Confirm likely subscriptions against receipts or your merchant account. If you suspect an unauthorized charge, contact your bank or card issuer right away.
Start With Every Payment Source
A checking-account statement does not show every subscription individually. It may show direct debits and one aggregated payment to a credit card, while the card statement contains the underlying merchant charges. A wallet or app store may use its own descriptor.
Build a source checklist:
- each checking and current account;
- every personal and business credit card;
- PayPal or another wallet’s automatic-payment list;
- Apple, Google, or other app-store subscription pages;
- household-member or employee cards for which you are responsible;
- invoices for subscriptions paid by transfer.
The statements provide the payment record. Merchant and platform accounts provide the contract, plan, renewal date, and cancellation controls. You usually need both.
How Much History Should You Review?
Review enough history to cover the longest likely billing cycle:
- monthly plan: several months can establish a pattern;
- quarterly or semiannual plan: cover at least one complete interval;
- annual plan: review 12 to 13 months;
- multi-year or irregular agreement: use the contract and older records.
Twelve months is a practical default, not a legal or mathematical minimum. If you changed cards, banks, or app-store accounts during the period, include both the old and new source.
Put the Transactions in One Working Table
Native bank or card CSV exports are preferable when they cover the required period and fields. If the only source is PDF, convert it to rows and validate the output against the statement.
A useful audit table contains:
| Field | Purpose |
|---|---|
| Source account | Prevents identical descriptors on two cards from being collapsed |
| Transaction date | Reveals cadence |
| Raw description | Preserves the exact evidence from the statement |
| Normalized merchant | Groups descriptor variants for review |
| Signed amount and currency | Distinguishes charges, reversals, and price changes |
| Candidate cadence | Monthly, quarterly, annual, irregular, or unknown |
| Owner or user | Identifies who recognizes or uses the service |
| Decision | Keep, change, cancel, dispute, or investigate |
| Renewal/cancellation date | Supports follow-up |
| Evidence | Receipt, merchant page, confirmation, or bank case number |
Do not overwrite the raw descriptor when normalizing it. Keep the source string and add a separate merchant label.
If your sources are PDFs, BankStatementLab exports CSV, XLSX, or JSON. It does not connect to a bank, card, wallet, or subscription platform, so you still need to gather every source and validate the extracted rows.
Find Recurring-Charge Candidates
A repeating descriptor is a clue, not proof. Flag candidates using several signals:
- similar normalized merchant name;
- same debit direction;
- same or similar amount;
- regular date interval;
- explicit terms such as membership, plan, hosting, cloud, or renewal;
- a prior receipt or renewal email.
Cadence should allow normal calendar variation. A monthly charge may move around weekends, and usage-based plans can vary in amount. Conversely, two identical purchases can be unrelated one-offs.
Useful candidate groups include:
| Pattern | What to investigate |
|---|---|
| Same descriptor and amount every month | Fixed monthly subscription |
| Same merchant with a changed amount | Price increase, tax change, tier change, or usage |
| One charge about a year apart | Annual renewal |
| Several services in one category | Possible duplicate need |
| App-store or wallet descriptor | Open the platform to identify the underlying service |
| Repeated unrecognized debit | Check the descriptor and receipts. If you suspect an unauthorized debit, contact the bank promptly. |
| Charge followed by a reversal | Cancellation, failed service, or correction—not ongoing net spend |
Do not classify a subscription from cadence alone. Confirm it through a receipt, merchant account, app-store list, contract, or the bank’s full merchant details.
Identify an Unknown Descriptor
Work from the least disruptive evidence to the most urgent:
- Search the exact raw descriptor and amount in email and receipt archives.
- Open the wallet or app-store billing history.
- Ask authorized household members or employees.
- Check the merchant account or contract.
- Search the descriptor online, recognizing that crowdsourced identifications can be wrong.
- Ask the bank or card issuer for the fuller merchant record and contact details.
- If the debit remains unrecognized, contact the issuer promptly about its dispute and blocking process.
A payment-processor prefix does not necessarily identify the underlying merchant. The location attached to a descriptor may be a billing or acquiring location, not where the purchase occurred.
Do not delay an unauthorized-transaction report merely to complete the full audit. Dispute rights and notification deadlines vary by payment method, issuer, and jurisdiction.
Decide: Keep, Change, Cancel, or Dispute
Keep
Keep a service when the current plan is used, the owner is known, the cost is understood, and the alternative would cost more or create unacceptable risk.
For business subscriptions, verify the number of seats, administrators, data-export process, and dependency before cancelling.
Change
Consider downgrading, reducing seats, moving from monthly to annual only when the commitment is justified, or replacing overlapping products. Confirm taxes, migration costs, lost features, and cancellation terms before comparing headline prices.
Cancel
Cancel through the merchant or platform where possible. Record:
- date and account used;
- effective cancellation date;
- final billing date;
- confirmation number or screenshot;
- data export completed;
- next statement date to verify.
Replacing or expiring a card may not stop a credential-on-file merchant. Visa’s official Account Updater documentation explains that participating issuers and merchants can exchange updated account information for recurring and card-on-file payments. Cancel the agreement itself and monitor the next statement.
For a U.S. consumer bank-account debit, revoke the merchant’s authorization and tell your bank or credit union. To stop a scheduled preauthorized transfer, give the bank a stop-payment order at least three business days before the transfer. Follow any request for written confirmation. Cancel the service separately with the merchant and settle any valid amount still due. CFPB guidance · Regulation E § 1005.10
Dispute
Report suspected unauthorized charges promptly. For a U.S. consumer credit-card billing error, call the issuer and send a written notice to its billing-inquiries address so it arrives within 60 days after the issuer sent the first statement showing the error. Use the issuer’s electronic process if it specifies one for written billing-error notices. Regulation Z § 1026.13
For an unauthorized debit-card transaction or other electronic transfer from a U.S. consumer bank account, notify the bank promptly. It generally must receive notice within 60 days after it sends the first statement showing the error. Report a lost or stolen debit card right away. Reporting within two business days of learning about the loss or theft can limit your liability. Regulation E § 1005.11 · Regulation E § 1005.6
Calculate the Annual Cost
Convert each verified recurring charge to an annual view:
- monthly fixed cost × 12;
- quarterly fixed cost × 4;
- annual plan = actual renewal amount;
- variable plan = actual trailing-period total or a clearly labeled estimate.
Track reversals and credits separately. Do not multiply one unusually high usage month by 12 and call it actual annual spend.
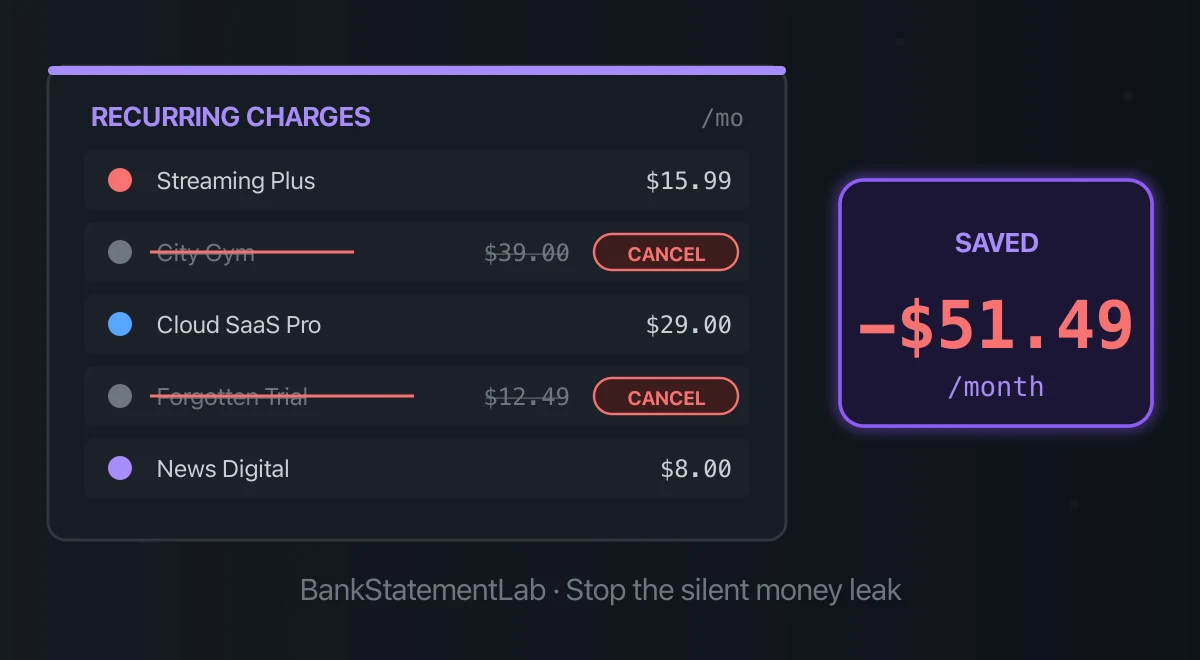
A $39.00 monthly gym membership and a $12.49 monthly subscription total $51.49 a month. If both cancellations take effect before the next charge and prevent 12 payments each, you avoid a projected $617.88 in charges over the next 12 months, before any fees or replacement costs.
For business services, add seat count and cost center. A small per-user charge can become material when unused licenses accumulate.
Common Audit Mistakes
- Reviewing only the checking account. Card subscriptions are hidden behind the card payment.
- Using only one month. Annual and quarterly renewals disappear.
- Treating two similar rows as proof. Verify the merchant and agreement.
- Combining currencies. Keep source currency explicit; do not total unlike currencies without a documented conversion.
- Ignoring reversals. Gross charges can overstate net cost.
- Cancelling access before exporting data. Back up data and transfer ownership first.
- Assuming a replaced card ends billing. Account-updater services can preserve authorized relationships.
- Failing to verify cancellation. Check the next statement and retain confirmation.
- Sharing a statement too widely. The audit file contains financial and personal information; restrict access.
Build a Lightweight Ongoing System
- Route recurring payments to a controlled card where practical.
- Maintain a tracker with merchant, owner, amount, cadence, renewal, and decision.
- Put reminders before trials and material annual renewals.
- Require approval for new business subscriptions and extra seats.
- Review monthly for unknown charges and quarterly for value, price, and usage.
- Reconcile the tracker to statements rather than trusting the tracker alone.
- Remove former employees and transfer account ownership during offboarding.
A quarterly interval is a useful habit, not a guarantee that every issue can wait three months. Unknown or unauthorized charges should be reviewed as soon as they appear.
Current US “Click to Cancel” Status
The Eighth Circuit vacated the FTC’s 2024 click-to-cancel amendments in July 2025. The FTC restored the prior Negative Option Rule in February 2026 and published an advance notice seeking comments in March. The Restore Online Shoppers’ Confidence Act still requires a simple way to stop recurring charges for the online negative-option sales it covers. Court decision · February 2026 Federal Register notice · FTC March notice · 15 U.S.C. § 8403
Cancellation and renewal law varies by jurisdiction and can change. Check current official guidance for your location and agreement.
Using BankStatementLab for the Spreadsheet Step
For unlocked statement PDFs, BankStatementLab can create CSV, XLSX, or JSON rows that are easier to group and filter. Review every extracted table against all source pages, especially amounts, signs, dates, and page boundaries. Matching totals alone cannot reveal offsetting missing transactions.
The signed-in upload screen accepts up to 15 files and 100 pages in total, with 50 MB per file. Source files are never stored on our servers. Failed extraction records are eligible for cleanup after 14 days. Keep your own originals.
Check the current credit allowances and extraction options on the pricing page.
Frequently Asked Questions
How many months of statements should I review?
Review at least one full likely renewal cycle. Twelve to thirteen months is a practical window for annual plans, but multi-year or irregular agreements can require older records. Include checking accounts, cards, wallets and app-store billing so every payment source is covered.
What if I can’t recognize a charge descriptor?
Search the exact descriptor and amount in receipts and email, then check wallets, app stores and authorized users. Ask the issuer for fuller merchant details if needed. If you suspect an unauthorized charge, contact your bank or card issuer immediately. Ask about its dispute process and how to block future charges.
Will cancelling a subscription hurt my credit?
Cancelling an ordinary paid service does not itself create a credit-account event, but an unpaid contractual balance or cancellation fee sent to collections can have consequences. Follow the agreement, retain confirmation and settle any legitimate final amount.
How do I tell a subscription from a one-off purchase?
Repeated merchant, amount and cadence make a useful candidate, not proof. Confirm the charge through a receipt, merchant account, platform subscription list or contract; usage-based subscriptions can vary and identical one-off purchases can repeat.
Do app-store charges count as subscriptions?
They can. An app-store descriptor can represent a subscription, an app purchase or another platform charge, so open the platform’s subscription and purchase history to identify the underlying service.
Should I audit my credit card statement or my bank statement?
Both. A checking statement shows direct debits and card repayments, while the card statement shows the merchants behind those repayments. Also review wallets and app stores, and compare transaction dates rather than statement-cycle labels.
How often should I redo the audit?
Monitor statements regularly for unfamiliar activity and schedule a periodic value review; quarterly is a practical cadence for many households and small teams. Review material renewals before their cancellation deadline, and investigate unknown charges immediately.
Conclusion
A good subscription audit is an evidence exercise: gather every payment source, cover the full renewal cycle, group candidates without erasing raw descriptors, verify the merchant, annualize the cost, record the decision, and confirm cancellation on a later statement.
If PDFs are the barrier to grouping the transactions, create a BankStatementLab account, export CSV, XLSX, or JSON, and validate the rows before using them. The tool prepares the table; you decide which agreements still earn their place.
Related Articles
Save hours every week
Turn your bank statements (PDF) into Excel, CSV or OFX, without manual retyping.