Save hours every week
Turn your bank statements (PDF) into Excel, CSV or OFX, without manual retyping.
For a U.S. conventional mortgage, statements are primarily used to verify ownership, availability and source of assets needed for closing or reserves—not to grade every purchase. Documentation depends on the loan program, automated-underwriting result and lender overlays. This article explains the underwriting purpose using Fannie Mae’s published rules as one concrete reference; ask your loan officer for the checklist that applies to your file.
Why Lenders Request Bank Statements
When statements are requested, the lender uses them with the rest of the file to verify assets, income or obligations relevant to qualification.
Verifying Your Income
Some deposits may corroborate income, but income documentation rules vary. A transfer or deposit should not be treated as earnings without a traceable source.
Confirming Your Down Payment and Closing Costs
A mortgage requires a down payment and closing costs, and lenders need to see that these funds are available, properly sourced, and from a source permitted by the loan program. Statements help establish ownership and availability; supporting records explain gifts, transfers and permitted borrowing. Ask the lender about the applicable source-of-funds rules.
Evaluating Financial Stability
Balances help show that verified funds remain available. Statement activity can also reveal transfers, debts or other facts that require clarification, but underwriting is governed by the program and complete file rather than a generic “responsible spending” score.
Meeting Regulatory Requirements
For Fannie Mae loans, B3-4.2-02, Depository Accounts says statements typically cover the most recent two months when they are used and explains how large deposits are evaluated. Other conventional, FHA, VA, USDA, jumbo and non-QM files follow different requirements.
Assessing Reserves
Many loan programs require borrowers to have reserves, meaning enough money left in the bank after closing to cover several months of mortgage payments. Your statements prove whether you meet this threshold.
What Lenders Look for: A Complete Breakdown
Mortgage underwriters are trained to scrutinize every page of your bank statements. Here is a detailed look at each element they examine and why it matters.
| Element Reviewed | What the Lender Checks | Why It Matters |
|---|---|---|
| Account holder name | Matches the name on the mortgage application | Confirms identity and ownership of funds |
| Account number | Consistent across all pages and statements | Ensures no pages are missing or swapped |
| Statement period | Covers the exact dates requested | Completeness of verification |
| Regular deposits | Frequency, amounts, and source of recurring income | Validates employment income and stability |
| Large or irregular deposits | Program-specific definition; Fannie Mae uses a 50% test for certain purchase files | May require evidence or exclusion from qualifying assets under the applicable rule |
| Available balance | Funds needed for the transaction and any required reserves | Confirms verified funds remain available |
| Potential obligations | Payments that may correspond to liabilities or support obligations | May need to be reconciled with the application |
| Account transfers | Transfers between accounts | Must be traceable to avoid double-counting assets |
How Many Months of Statements Do You Need?
The number of months required depends on the type of loan you are applying for and your employment situation.
| Loan Type / Scenario | Statements Required | Notes |
|---|---|---|
| Fannie Mae file using statements for depository assets | Typically the most recent 2 months | The guide permits other approved verification methods |
| Other conventional or government-backed loan | Ask the lender | Program rules and lender overlays differ |
| Non-QM bank-statement income program | Ask the lender for the program checklist | This is distinct from ordinary asset verification |
| Gift funds | Follow the applicable program documentation | Do not assume the donor must always provide the same documents |
Note that individual lenders may have additional requirements beyond these minimums. It is always best to ask your loan officer exactly what they need before you start gathering documents.
Understanding “Sourced” and “Seasoned” Funds
Two terms come up frequently in mortgage underwriting, and understanding them can save you significant headaches.
Sourced funds means the lender can trace exactly where every significant deposit came from. If you deposited a check, they want to know who wrote it and why. If you transferred money from another account, they want to see the originating account statement as well.
“Seasoned funds” is industry shorthand, not a universal exemption after exactly 60 days. What must be documented depends on the statements reviewed, deposit type, transaction and loan program.
Want to review requested statements internally? BankStatementLab extracts PDF rows to Excel, CSV or JSON. Unlock protected files before upload and compare every extracted table with all original pages; a matching total alone does not prove completeness. Keep the original bank-issued PDFs for submission unless the lender asks for another format. Try it →
Items that may require documentation
These are common sources of follow-up, not automatic reasons for a particular decision.
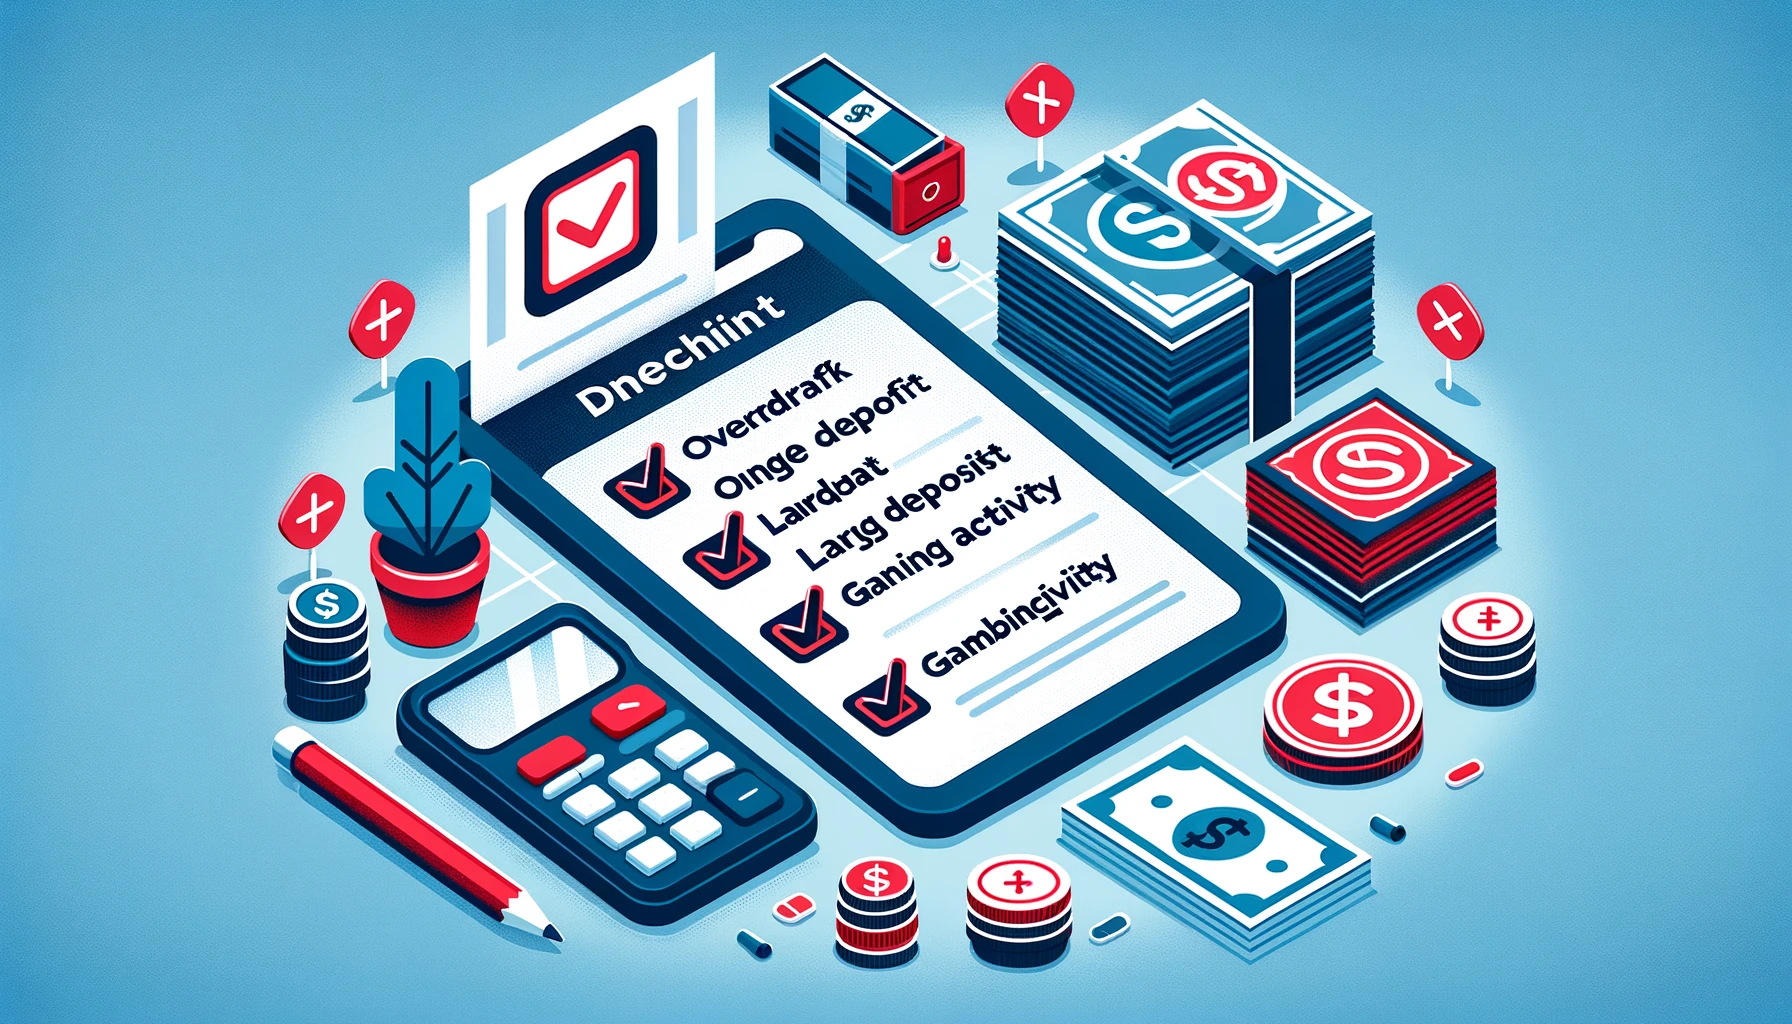
1. Large Unexplained Deposits
Fannie Mae defines a large deposit for certain purchase transactions as a single deposit exceeding 50% of total monthly qualifying income, with detailed exceptions and treatment in B3-4.2-02. That definition is not universal across all programs. Keep source documents for material non-payroll deposits, transfers, gifts and asset sales, and follow the underwriter’s request.
2. Overdrafts and Non-Sufficient Funds (NSF) Charges
Returned items or overdrafts may prompt questions about balances or obligations. An isolated event is not governed by a universal automatic-decision rule; provide an accurate explanation if requested.
3. Undisclosed Recurring Payments
Recurring payments may correspond to liabilities or support obligations that must be considered under the loan program. Disclose requested obligations accurately and provide context; not every subscription or recurring merchant charge is debt.
4. Patterns of Cash Deposits
Cash deposits can be difficult to source. If the funds are needed for the transaction, ask the lender what evidence the program accepts rather than changing legitimate activity to manufacture a particular pattern.
5. Sudden Spikes or Drops in Your Balance
A balance change may be an internal transfer, verified sale, normal expense or new obligation. Trace both sides and retain source documents.
6. Unmatched or altered records
Missing pages, edited statements or inconsistent account ownership undermine verification. Submit complete, unaltered bank-issued records and answer document requests accurately.
How to Prepare Your Bank Statements Before Applying
Ask for the lender’s document checklist early, then review completeness and source evidence before submission.
Preserve source evidence
Use normal, lawful payment methods and retain records showing where material funds came from. Do not structure activity merely to avoid review.
Trace transfers between accounts
If you move funds, preserve statements showing both sides. Ask the lender before consolidating assets when documentation requirements are unclear.
Check statement completeness
Confirm that every page is present, the name and account details are visible as required, and the period matches the request. Do not edit transaction history.
Document Gift Funds Early
If a family member is helping with your down payment, get the gift letter prepared in advance. The letter should state that the funds are a gift, not a loan, and include the donor’s name, relationship to you, the amount, and the date of the transfer. Ask the lender which transfer evidence it accepts; donor statements are not the only possible method. Fannie Mae’s personal-gift rules describe the letter and acceptable transfer documentation.
Resolve Any Irregular Activity
If you have any transactions that might look questionable, prepare explanations now. Write a brief letter for each unusual deposit or withdrawal, and gather supporting documents such as sale receipts, insurance claim letters, or bonus payment confirmations from your employer.
Organize Your Statements
Make sure you have complete, unaltered statements for all accounts you plan to use. Every page must be included, even blank pages that say “this page intentionally left blank.” Missing pages are a common reason for document re-requests that slow down the process.
Preparation Checklist at a Glance
Use this checklist to make sure you are ready before submitting your mortgage application.
- Gather the exact accounts and period requested by the lender
- Ensure all pages are included and legible
- Prepare source evidence for deposits or transfers identified by the underwriter
- Follow the program-specific gift-fund documentation request
- Verify your name and account details are consistent across all documents
- Ensure balances support your down payment, closing costs, and required reserves
- Confirm recurring deposits match your declared income
Making Your Statements Work for You
Your bank statements do not have to be a source of anxiety. With the right preparation, they become one of the strongest parts of your mortgage application. Lenders are not looking for perfection. They are looking for consistency, transparency, and evidence that you can comfortably afford the home you want to buy.
The key takeaway is simple: the fewer surprises your bank statements contain, the smoother your mortgage process will be. Start early, stay organized, document everything, and you will walk into the application process with confidence.
If your bank statements are in PDF format and difficult to review or organize, converting them to a clean spreadsheet format can help you spot potential issues before your lender does. A clear, structured view of your transactions makes it easy to identify anything that might need an explanation and ensures nothing catches you off guard.
Ready to review the requested PDFs? BankStatementLab extracts statement rows into Excel, CSV or JSON for internal checking. Submit the original statements unless your lender requests the extracted file. Get started →
Save hours every week
Turn your bank statements (PDF) into Excel, CSV or OFX, without manual retyping.